The S&P 500 Isn't as Diversified as You Think (It Acts Like 48 Stocks)
Philipp 12:47 Episode 6 of Ask a Banker
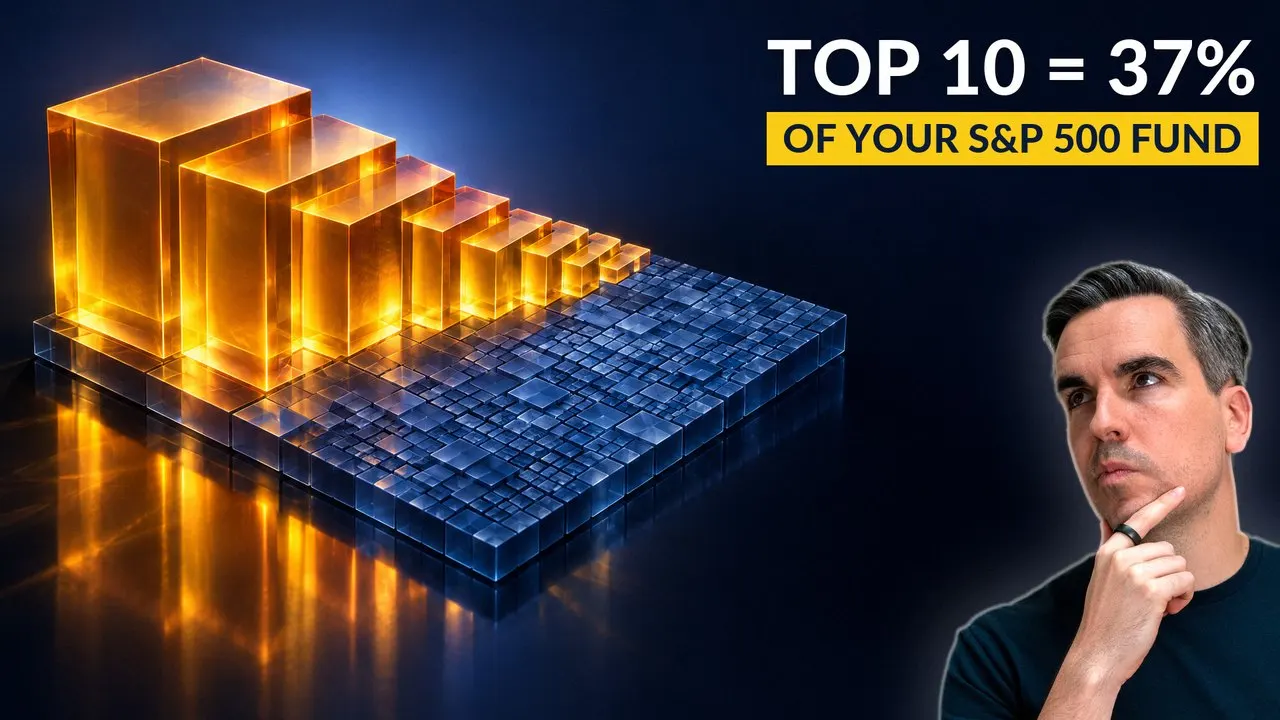
The S&P 500 Isn't as Diversified as You Think (It Acts Like 48 Stocks)
Transcript
The spoken text of the video, published November 10, 2026, lightly edited for reading. Where the video and the article differ, the article is the checked version.
Should you still just buy the S&P 500? Well, it holds 500 companies, but it behaves like about 48. And the answer is still yes. Nothing here is a reason to stop. But you are buying something more lopsided than you were told, and this is worth a few minutes to know the shape of it.
The 48 doesn’t mean that 450 of them quietly went missing. It means the money is stacked so unevenly that the whole thing now moves as though you would only hold 48 of them.
Diversification is how many things you own. Concentration is how evenly you own them. The S&P 500 scores brilliantly on the first and badly on the second, at the same time. Put just 100,000 in this morning and about 8,000 of it lands in just one company. You still own 500 companies, that’s true, but you just don’t own them evenly, and that was always the deal.
In 2025 and again in 2026, two of the largest fund companies on earth asked their own shareholders for permission to stop being diversified, and I’ll show you the paperwork.
And the odd thing about this whole argument in 2026 is actually who’s having it. In the past it used to be the norm: fund managers attacking index funds. Now it’s index investors on their own forums, quietly checking whether they’ve been the last one to notice something. People who did the boring, correct thing for 10 years and have started to wonder whether the boring, correct thing has turned into a different thing while they weren’t looking.
The posts in the forums have titles like “Am I missing something about the S&P 500?” Underneath, the same two replies every time. Nothing has changed: same fund, same method, and it never promised you equal weights. Or: 10 positions, 37% of your money, and that stopped being diversification a while ago.
Both get upvoted hard. And then further down sits the line that gets more agreement than either one of them, and it isn’t an answer at all: whichever one I pick, the other one is going to perform better.
That is not an investing question. It’s a regret question, and that’s an honest one. Really. Many of us have sat there, not because the numbers were hard, but because we all just kept thinking that owning the index means you do not have to think about this. And then I had to go and check whether this is still true, and now suddenly I do have to think about it.
Okay, so let’s take the 100,000 from the beginning and take it apart, because percentages don’t land until they’re money. The second-largest company in the list takes another 7,000, and the 10 biggest positions together about 37,000 of it. And the remaining 490 companies divide up the rest.
None of that is hidden. Every one of those numbers is published. It’s just not the number anyone quotes, but it does change the shape of the question. It stops being “is this a good fund?” and it becomes “do you know what you own?” Because if you bought this on the sentence “it’s 500 companies, so it’s diversified”, the sentence is still true, and the thing underneath has just moved.
[Note: The video’s figures are from August 2026. Recalculated from fund holdings as of November 5, 2026: about $7,900 in the largest company, $6,900 in the second, $37,600 in the 10 largest positions.]
But it’s still 500 companies, right? Yes, technically that’s true. You own every one of them this morning. Nothing was taken away from you. What moved is the weighting, and the weighting is doing precisely what it was built to do. A market-cap index never promised to spread your money evenly. It promised to own the market the way the market owns itself. When a handful of companies get very large, your fund gets very concentrated. That is the mechanism working, not failing.
Nothing broke. The index kept its promise. So you’re not late to something. You’re early to reading the label.
And this is where it stops being a forum argument and starts being a paper trail. “Diversified” on a fund isn’t a description. It’s a legal threshold, and it has a ceiling: everything you hold above 5% of the fund has to fit inside a quarter of it. In the S&P 500 today, four companies are each over that line, and together they fill the quarter completely. Well, 25.8% against the ceiling of 25, if you want to be exact about it. Slightly over. Which isn’t a violation, because the test applies on the day you buy, and a position that grows past the line by going up is fine. Nobody has broken anything. But the fund companies could see the ceiling coming.
[Note: 25.8% is the weight of the four companies above 5% on August 27, 2026. On November 5, 2026, three companies were above the line, together 21.1%. This figure moves with prices.]
August 2025. Vanguard tells its shareholders it intends to give up the diversified status on two of its sector index funds, and it puts it to a vote. The reason, in the press release: “the diversification limits constrain funds’ ability to directly invest in securities in proportion to their weights in their respective benchmarks, as the benchmarks have become increasingly concentrated in a small number of stocks.”
Read that once more, because of what it actually says. The rule that exists to keep a fund diversified had started getting in the way of tracking the index. So the rule went.
None of that was your fund. But it is the same pressure, coming from the same four companies. And it kept going. 14 other Fidelity funds had already done that.
[Note: Vanguard’s two funds track health care and financials indexes, so the pressure there came from other companies, not the four above. Fidelity’s earlier changes came before Vanguard’s, mostly in actively managed growth funds: shareholders of 14 funds were asked to approve them, and Fidelity gave the managers’ flexibility as the reason.]
Actually, I’ve seen a ton of these limit breaches from the inside. It isn’t as dramatic as you might think. Nobody panics about it, it’s just daily business. It’s a line in a monitoring report that just turned amber, and then somebody has to decide whether to trim the position or to keep it, because nothing actually went wrong. The position just got too big. That’s just one of those “no fun at all” meetings.
Now, three honest limits, because this is exactly where a video like this normally overreaches.
First, those rules don’t bind your S&P 500 fund the way people assume. A diversified fund is legally allowed to run roughly double the concentration the index actually has. So if you’ve read that the rulebook is what holds active managers back, that is backwards.
Second, this is not a record. S&P Dow Jones Indices put it carefully: a level of concentration “not seen since the 1960s.” Not seen is very different from never seen. It has come down before, sometimes because the big ones fell, sometimes because everything else caught up. But nobody gets to tell you which of those is next.
[Note: S&P Dow Jones Indices wrote “not seen since the mid-1960s”.]
And third, this is the uncomfortable one, because it’s what the comment section always asks. If the money keeps pouring into index funds, doesn’t that push the biggest companies up all by themselves? The research says yes. Passive flows lift the largest firms more than the rest, and this works even when nobody puts a new dollar in, just moves the money out of an active fund into a passive fund. So some of this crowding is self-inflicted, including you and including me.
[Note: The study (Jiang, Vayanos and Zheng, Review of Financial Studies, 2025) shows the “no new dollar” effect for the market as a whole: it can rise even when money only moves from active to passive funds.]
So should you pay someone else to hold something different instead? Does that solve the problem? Take the US large-cap funds that finished 2021 in the top quarter of their category, all 164 of them, and then follow them year by year. After 12 months, 20% are still in the top quarter. After 24 months, none of them. Not a small number. None. And it was still none of them at the end of 2025. And the fund you’d have picked in 2005: two out of three of them don’t exist anymore.
[Note: “None” means that no fund stayed in the top quarter at every year-end after 2021 (S&P Dow Jones Indices, U.S. Persistence Scorecard, Year-End 2025). The article gives the second test from the same report.]
Now the part that actually cuts against me, and almost nobody includes it. Count funds, and 79% of them lost to the index in 2025. Count dollars, and the average active dollar beat it in the same year. Both of those are true, because the money isn’t spread evenly across the funds either. Over 5, 10 and 20 years, the gap goes firmly back to negative.
And the real constraint on a manager isn’t the rulebook, it’s the plumbing. Equity funds hold about 1.6% of their money in cash, and by law a fund has seven days to pay you back if you want out. That is their entire margin. A manager who decides this market is too crowded has to sell into the crowd first, then sit on the cash while the thing he sold carries on going up, and then explain a full year of lagging the index to people who can take their money out on a Tuesday, which is a nerve problem more than an intelligence problem. Or at least that is the half of it nobody puts in the brochure. And that’s their job.
[Note: The Investment Company Institute measures liquid assets, not only cash. Its latest figure, for September 2026, is 1.5%.]
What do I think about all this? The people who kept buying the same fund every month through all of this have done better than almost anyone I’ve watched trying to be clever about it. In the long run, this is not decided by concentration. It’s about not giving yourself the opportunity to think too long about this and miss the very market growth you’re actually investing for.
So, plainly: your index fund is still diversified. But it’s more concentrated than people think. That is not a reason to panic, it is a reason to know what you own. Keep buying it. You hold 500 companies weighted by size, and the size is currently unusually top-heavy. This is a property of the method and not a fault of the fund.
Two things get offered as a fix. Neither of them actually is. Going global halves the problem and doesn’t solve it. Move from a US index fund to a total world fund, and the top 10 drop from around 37% of your money to about 21%. That’s nearly halved. Still the largest thing you own, because those companies are still the largest in the world. And equal weighting is not a return to neutral. It’s an active bet that the biggest companies will do worse than the rest. It has costs, it has turnover, and it wins in some decades and loses badly in others. It is a position. It just doesn’t feel like one, because it sounds fair.
So there is only one thing actually worth deciding, and it isn’t which fund to buy. It’s whether you want your money to follow the world’s biggest companies or the world’s companies. Both are defensible. Only one of them is what you own this morning.
And the number from the top: 48. That is how many equally weighted stocks the S&P 500 currently behaves like. You still own 500, you just don’t own them evenly. And that was actually always the deal.
[Note: 47.5 is the figure for July 31, 2026, derived from S&P Dow Jones Indices data. Recalculated from fund holdings as of November 5, 2026, it is about 46.]
Three things to take home. And a note: this is education, not financial advice. Your situation is yours.
First, open your fund’s prospectus and search the word “non-diversified”. If it isn’t there, your fund is still inside the old box. If it is in there, and on some funds it is now, the manager is allowed to run more concentrated than the rule permitted. This is not a warning that something is wrong. It is a change in what you agreed to, and that happened by letter.
Second, stop counting positions. 500 tells you almost nothing. The number that tells you what you own is the top-10 weighting. It is on the first page of every fund fact sheet, and it takes about 20 seconds.
Third, if you decide you want less of this, redirect the next money instead of selling what you already hold. In most places selling has a tax bill attached, and the bill is certain while the benefit is not. Worth having that part looked at for your own situation before you act on it.
The label on your fund never said “evenly”. It said “the market”. And the market is currently shaped like this. That doesn’t make it broken, and it doesn’t make you the last one to notice. It makes you someone who knows the shape of the thing he owns, which is the only version of this that lets you stop opening the app to check whether something changed while you weren’t looking.
And if the answer isn’t to switch funds, the next question is whether it’s worth paying a person to answer these for you. Is a financial advisor worth the money? That’s next. I’m Philipp. Stay skeptical, and see you in the next one.
The S&P 500 holds 500 companies, but measured by how the money is spread across them it behaves like about 48 equally weighted stocks. What that means for an index fund you already own. Episode 6 of Ask a Banker.
Read the written version
Index Fund Risk: How Concentrated Is Your S&P 500 Fund, Really?
An S&P 500 index fund is still diversified across about 500 companies, but its money is concentrated: in a large S&P 500 fund on November 5, 2026, the 10 largest positions held 37.6% of the assets, and the weights were spread as if the fund owned about 46 stocks of equal weight. That is how a market-cap weighted index works, not a fault in the fund and not by itself a reason to sell; a large S&P 500 fund's own prospectus says it may become non-diversified solely because of changes in market capitalization or index weighting. An active fund can hold less of the largest companies, but picking one that does so and keeps beating the index has not been reliable; in a total world fund, the top-10 share was 44% lower than in an S&P 500 fund (August 27, 2026), close to half. The practical check is the top-10 weight on the first page of the fund's fact sheet.
Full article, with the sources and the numbers →
More from Ask a Banker
-
 Should You Buy a Rental Property? (Real Estate vs Stocks) Episode 1 · 12:30
-
 The Worst Month for Stocks Isn't October (Data Since 1928) Episode 2 · 12:07
-
 Is Gold a Good Investment? Central Banks' Reason Isn't Yours Episode 3 · 12:02
-
 Live Off Dividends: How Much You Need Invested for $2,000 a Month Episode 4 · 8:48
-
 Warren Buffett's Investment Strategy: The Part You Can't Copy Episode 5 · 13:23